How Does LendingTree Get Paid?
LendingTree is compensated by companies whose listings appear on this site. This compensation may impact how and where listings appear (such as the order or which listings are featured). This site does not include all companies or products available.
LendingTree is compensated by companies whose listings appear on this site. This compensation may impact how and where listings appear (such as the order or which listings are featured). This site does not include all companies or products available.
Home Refinance
A refi could open up room in your budget and unlock funds for what's next.

Refinancing, by the numbers*

$2,320
Average annual customer savings by home refinancing

$44,837
Average life-of-loan savings by comparing refi offers through LendingTree

$96,805
Average amount of cash LendingTree customers access through cash-out refi
Find your best rate on our network of 140+ lenders
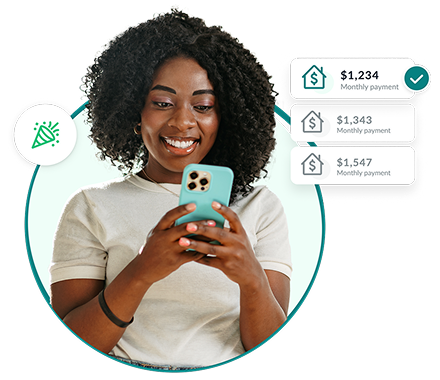
Turns out, there are two reasons to refinance
Both replace your current mortgage with a new one. The difference is what your goals are.
Refi to access cash (cash-out refinance)
- Replaces your mortgage with a larger loan
- You receive the difference in cash at closing
- Use the funds for renovations, debt consolidation or other expenses
- Best for accessing equity alongside a mortgage refinance
Refi to pay less (rate-and-term refinance)
- Replace your current mortgage with a new one — same balance, different terms
- Doesn't convert your equity to cash
- Can lower your rate, monthly payment, or both
- Best for saving money on existing loan
A look at home refi rates on our network
Before you refinance, here's what to know
The right refinance isn't just about the rate. The smartest move depends on what you gain, what you pay and how long you'll benefit.
If rates have dropped, your credit has improved, or your goals have changed since you got your mortgage, a rate-and-term refinance could mean a lower payment or a faster payoff — without changing how much you owe.
Yes. Expect 2-6% of your loan amount, which typically covers things like appraisal, title, and origination fees. Some lenders let you roll costs into the loan, though you'll pay interest on them too.
Sooner than you might think. Some lenders allow it within months of closing on your current loan. The right timing depends on your lender and loan type, and whether the math actually works in your favor.
A lower monthly payment doesn't always mean lower costs overall. Extending your loan term can mean paying more interest over time, and refinancing comes with upfront costs you'll need time to recoup. It's worth knowing what you're trading off, not just what you're saving.
Run the numbers on your refinance
Your monthly payment
$1,580.17/mo.
Total Repayment:
$568,861.22
Payment Breakdown
Principal Amount
$250,000.00
Total Interest Paid
$318,861.22
Should you get a home equity loan or a cash-out refi?
A home equity loan might make more sense if you want to keep your current mortgage and rate. A cash-out refi might make more sense if you want to access your equity, and you also qualify for better rates or terms by refinancing.
Simple. Fast. Secure.
Ready to get started?
-
Tell us about your mortgage
Answer a few quick questions about your current loan and what you're looking for.

-
Shop your offers
Compare rates and terms from multiple lenders, side by side, based on what you qualify for.

-
Choose your refinance
Pick the offer that fits your goals.

No credit impact
*Based on LendingTree Studies